GADGETS
Apple Widened Its Tablet Lead on a 0.1% Inventory Rise
Q1 tablet shipments rose 0.1% on extra stock, not demand. Apple grew on iPad Air while Samsung’s cheaper Tab S11 lost volume.

Global tablet shipments rose 0.1% to 37 million units in Q1 2026, a gain Omdia traces to extra stock in the channel, not to people buying more slates. Apple still led with 14.8 million iPads, a 40.1% share, while Samsung’s Galaxy Tab S11 spent the whole quarter on sale and Samsung still shipped fewer tablets than a year earlier.
Latin America led the regional print, then the Middle East and Africa. Shipments still fell from Q4 2025, which is the usual first-quarter pattern. The year-on-year bump was 49,000 units on a base of 36.971 million.
Q1 Added 49,000 Tablets on a 37 Million Base
Omdia’s PC Horizon tracker, which counts sell-in to the channel rather than boxes leaving stores, put the quarter at 37.020 million units. That is shipments rising just 0.1 percent from Q1 2025. Apple, Huawei, and Lenovo added volume. Samsung, Xiaomi, and the long tail of smaller brands gave it back.
Q1 AND Q2 2026 TABLET SHIPMENTS
| Vendor | Q1 2026 | Q1 change | Q2 2026 | Q2 change |
|---|---|---|---|---|
| Apple | 14.8 million | +7.9% | 13.5 million | -7.5% |
| Samsung | 5.8 million | -12.6% | 5.8 million | -13.0% |
| Huawei | 3.2 million | +28.1% | 2.7 million | -15.6% |
| Lenovo | 3.0 million | +20% | 3.9 million | +27.1% |
| Xiaomi | 2.6 million | -13.6% | 2.8 million | -6.8% |
| Others | 7.4 million | -11.9% | 6.8 million | -23.5% |
| Total | 37 million | +0.1% | 35.6 million | -9.9% |
Omdia rounded those Q1 line items in its May 7, 2026 note; the underlying tracker is in thousands of units. Apple’s 40.1% share is the Q1 figure. By Q2 its share was 37.8% in a smaller market, and it was still first.
Vendors Pushed Tablets Down the Priority List
Himani Mukka, research manager at Omdia, had already described the category as a leftover before the Q2 drop arrived. Phone groups were steering parts and marketing toward handsets. PC groups were steering them toward notebooks and desktops. Tablets sat in the middle with weaker margins and no forced upgrade cycle on the scale of Windows 10 leaving support.
Heading into 2026, tablets have been relegated in importance for vendors across margins, volume, and overall value. In this supply-constrained environment, consumers and vendors alike are being more deliberate about which devices to prioritize.
Himani Mukka, Research Manager, Omdia
Mukka said the 2026 mix would tilt toward premium models, where demand had held up better than the mass market. Volume tablets, she said, had little room left for promotions once memory and other parts got more expensive, and they lacked a structural refresh catalyst. That is the mechanism behind a 0.1% shipment print that still felt empty: brands filled warehouses, then spent the rest of the year arguing over which SKUs were worth the parts.
What the Tab S11 Costs Against iPad
Samsung’s flagship slate was not a late arrival into that squeeze. The company unveiled the Galaxy Tab S11 series on September 4, 2025, and put it on sale the same day, so every week of Q1 2026 was a Tab S11 week. The U.S. newsroom said the Galaxy Tab S11 starts at $799.99 for the 11-inch model, with the Tab S11 Ultra from $1,199.99, S Pen in the box, IP68, and up to seven Android upgrades.
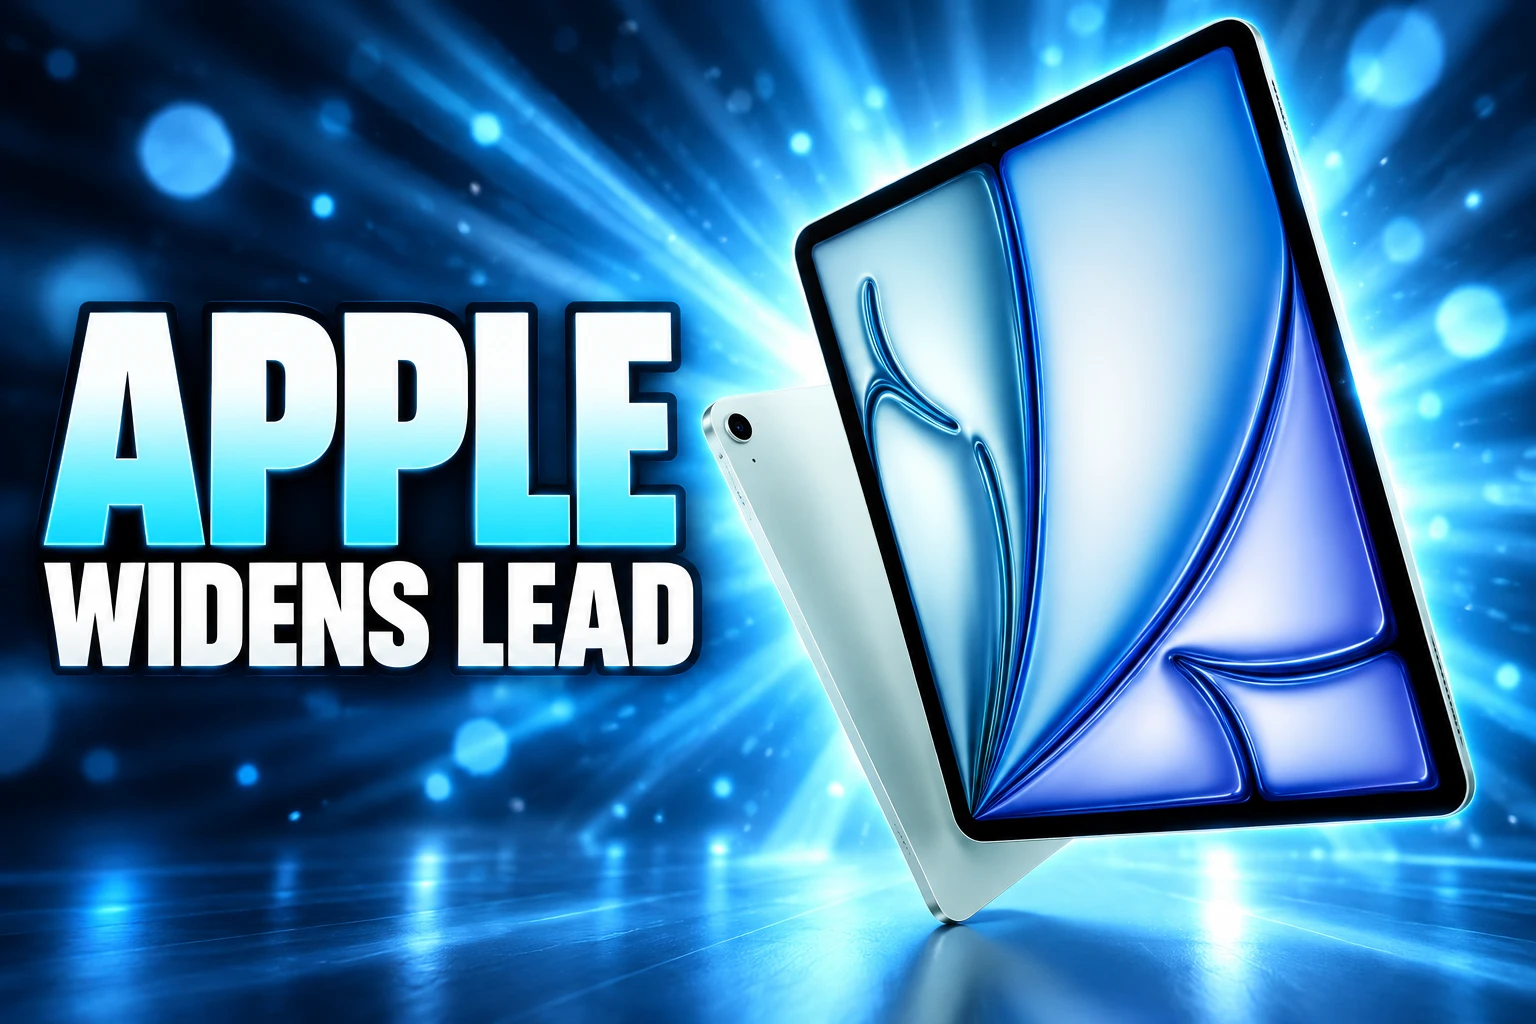
Apple’s volume engine in the same Omdia note was not the Pro. It was iPad Air. On March 2, 2026, Apple introduced an M4 Air, with pre-orders on March 4 and shelves from March 11, so it only caught the last three weeks of the quarter. Even so, Omdia credited Air for Apple’s 7.9% shipment gain. The 11-inch iPad Air starts at $599 for Wi-Fi, with the 13-inch from $799, $50 less for education on the small size.
LAUNCH PRICES THAT SAT IN THE CHANNEL
| Model | U.S. start price | On sale from |
|---|---|---|
| Galaxy Tab S11, 11-inch, 128GB Wi-Fi | $799.99 | September 4, 2025 |
| Galaxy Tab S11 Ultra, 256GB | $1,199.99 | September 4, 2025 |
| iPad Air, 11-inch, 128GB Wi-Fi | $599 | March 11, 2026 |
| iPad Air, 13-inch, 128GB Wi-Fi | $799 | March 11, 2026 |
The Tab S11 can undercut iPad Pro and still sit above the Air that actually moved Apple’s number. Samsung shipped 5.8 million tablets in Q1, down 12.6% from 6.633 million a year earlier, and Omdia flagged pricing pressure on the brand. A $799 Android flagship with a bright AMOLED panel and a free stylus is a serious product. It was not a 5.8 million-unit product in a quarter Apple closed at 14.8 million.
The Back-to-School Quarter Lost Its Seasonal Lift
The inventory warning did not stay theoretical. Omdia’s August 6, 2026 tracker put Q2 shipments at 35.6 million units, down 9.9% from 39.481 million in Q2 2025. For the first time in years, the second quarter also failed to rise from Q1, the usual back-to-school step-up. Mukka called it among the steepest declines over the past two years.
The global tablet market entered its expected downturn in Q2 2026, with shipments falling 10% YoY. Discover what’s driving the market correction and how vendors are responding: https://t.co/CSee9xIRVF#ConsumerTechnology
— Omdia (@OmdiaHQ) August 6, 2026
Apple still led, at 13.5 million iPads, but that was a 7.5% year-on-year drop, and the standard iPad did most of the volume, with Air and mini a smaller slice. Samsung was again second at 5.8 million, down 13.0%. Its unit count barely moved from Q1, yet the year-on-year hole stayed open. Huawei’s Q1 surge reversed, to 2.7 million, down 15.6%. Xiaomi eased to a 6.8% decline. The residual “others” bucket fell 23.5%, the worst drop on the table, which is what a parts shortage does to cheap white-label slates first.
FROM THE 2025 RECOVERY TO THE 2026 BREAK
- 2025: Global tablet shipments rise 9.8% to 162 million units, Omdia’s highest annual shipment volume since 2020.
- September 4, 2025: Samsung puts Tab S11 on sale from $799.99 and Tab S11 Ultra from $1,199.99.
- Q4 2025: Shipments reach 43.8 million, up 9.8%. Apple ships 19.6 million iPads, a 44.9% share, up 16.5%, on iPad (11th generation) and M5 iPad Pro.
- March 11, 2026: M4 iPad Air arrives from $599.
- Q1 2026: Shipments hold at 37 million, up 0.1%, a rise Omdia ties to inventory build-up.
- May 7, 2026: Mukka warns that second-half 2026 will stay cautious, with volume models under the most pressure.
- Q2 2026: Shipments fall to 35.6 million, down 9.9%, and miss the usual sequential back-to-school lift.
Mukka said the late-2025 lift mixed holiday demand with vendor pre-build ahead of expected memory shortages. That pre-build is the same sell-in trick that padded Q1. Once the extra cartons were in the channel, Q2 had to ship against both weaker end demand and higher bill-of-materials costs. Consumers delaying purchases as prices rose is the other half of her Q2 note.
Lenovo Kept Growing After Huawei’s Surge Reversed
Lenovo is the exception that still fits the inventory story. It shipped 3.0 million tablets in Q1, up 20%, on a mix of education deals and shipment pull-in. In Q2 it was the only name in Omdia’s top five to grow, to 3.9 million units, up 27.1%, and it jumped from fourth to third. Omdia said some of that was real end-user demand. It also said Lenovo sold extra units into the channel ahead of expected price increases and big retail events, which is another way of filling warehouses before the parts bill goes up.
Huawei’s path ran the other way. Q1 volume of 3.2 million, up 28.1%, was the fastest gain among the leaders and moved the company to third globally on Asia Pacific expansion. Q2 volume of 2.7 million, down 15.6%, dropped it to fifth. A one-quarter spike that fades is what a pull-in looks like after the fact. Xiaomi never got the spike: 2.6 million in Q1, down 13.6%, then 2.8 million in Q2, still down 6.8%, which is the mass-market tablet problem in one brand.
Samsung’s share actually ticked up to 16.3% in Q2 because the whole market shrank faster than its own 5.8 million-unit run rate. That is a cold comfort share gain. Omdia said Samsung would keep shifting mix toward higher-margin models as component supply stayed tight, which is another way of saying the cheap Galaxy tabs get fewer chips.
Chromebooks Show the Same Tight Memory Math
Omdia filed Chromebooks next to tablets because education budgets and memory prices hit both. Kieren Jessop, principal analyst at Omdia, said Chromebooks were the most damaged PC category in Q1, with production signals weak and school deployments slipping until conditions settle. Japan’s GIGA School Program 2.0 is in that slipstream: the first phase ran through the end of 2025, and Jessop said the supply mess is likely to delay the next phase.
CHROMEBOOK VENDORS IN Q1 2026
- Lenovo: First place at 1.5 million units, down 11.2%, after the first GIGA phase ended, with NEC in that Japan mix.
- HP: Second at 1.0 million units, down 15.3%.
- Acer: Third at 937,000 units, a milder drop, helped by North America and more units into Asia Pacific.
- Dell: 413,000 units, down 28.3%, the steepest fall among the five.
- ASUS: 406,000 units, up 3.5%, the only gainer, on a 9% share and a GIGA 2.0 role.
Q2 Chromebook shipments were 5.4 million, down 8.6% from 5.926 million. Omdia said memory now takes a swollen share of the parts list on budget and school machines, which is why that category keeps shrinking even when a vendor such as ASUS can still grow on a named education contract. Tablets without a premium badge sit on the same bill.
Flagship Models Get the Parts That Remain
Mukka’s Q2 note is the policy that follows the 0.1% print. Vendors, she said, are unlikely to put the whole tablet category first while components stay scarce. They will spend the limited supply on flagship and premium models, then try to make the rest of the revenue on software, AI features, and new go-to-market plans. Omdia’s rest-of-2026 forecast assumes cheap tablets stay scarce and buyers wait as prices rise.
That is already visible in the mix. Apple can grow in a flat quarter on iPad Air and still lose units in the next quarter when the standard iPad has to carry the load. Samsung can sell a $799.99 Tab S11 for a full quarter and still post a 12.6% shipment drop. Lenovo can keep growing by feeding education channels and pulling shipments forward. Huawei can jump 28.1% and give it back. The 37 million-unit quarter was never a demand recovery. It was the last of the 2025 stock-up, counted as growth because the boxes had left the factory.

Instagram Plus Tests a Read-Only Mode That Cuts Stories

Altman Asks the Public to Accept Some AI Harm

Google Freezes OSS VRP Product Reports After AI Flood

AI Agents Make Payment Rails the Scarce Prize

Turkey’s Crypto Boom Now Runs Through Three Banks

Fable 5 Came Back Under a Commerce On-Off Switch

Google’s SpaceX GPU Lease Has a Sept. 30 Deadline

Plasma One’s XPL Locks Face a 1.81 Billion Cliff

DGO’s Rs 549 World Cup Pass Cost Fans Sleep and Data

Moonshot AI’s $30 Billion Ask Became a $35 Billion Close
-
 AI4 months ago
Fable 5 Came Back Under a Commerce On-Off Switch
-
 AI4 months ago
Google’s SpaceX GPU Lease Has a Sept. 30 Deadline
-
 CRYPTO4 months ago
Plasma One’s XPL Locks Face a 1.81 Billion Cliff
-
 APPS4 months ago
DGO’s Rs 549 World Cup Pass Cost Fans Sleep and Data
-
 AI4 months ago
Moonshot AI’s $30 Billion Ask Became a $35 Billion Close
-
 NEWS4 months ago
ColorOS 17 Device List Spans Oppo, OnePlus and Realme
-
 GAMING4 months ago
Xbox Cuts 3,200 Jobs After Five Years of Thin Returns
-
 GAMING4 months ago
The RTX 4050 Under Rs 70,000 Hides a Wattage Gap